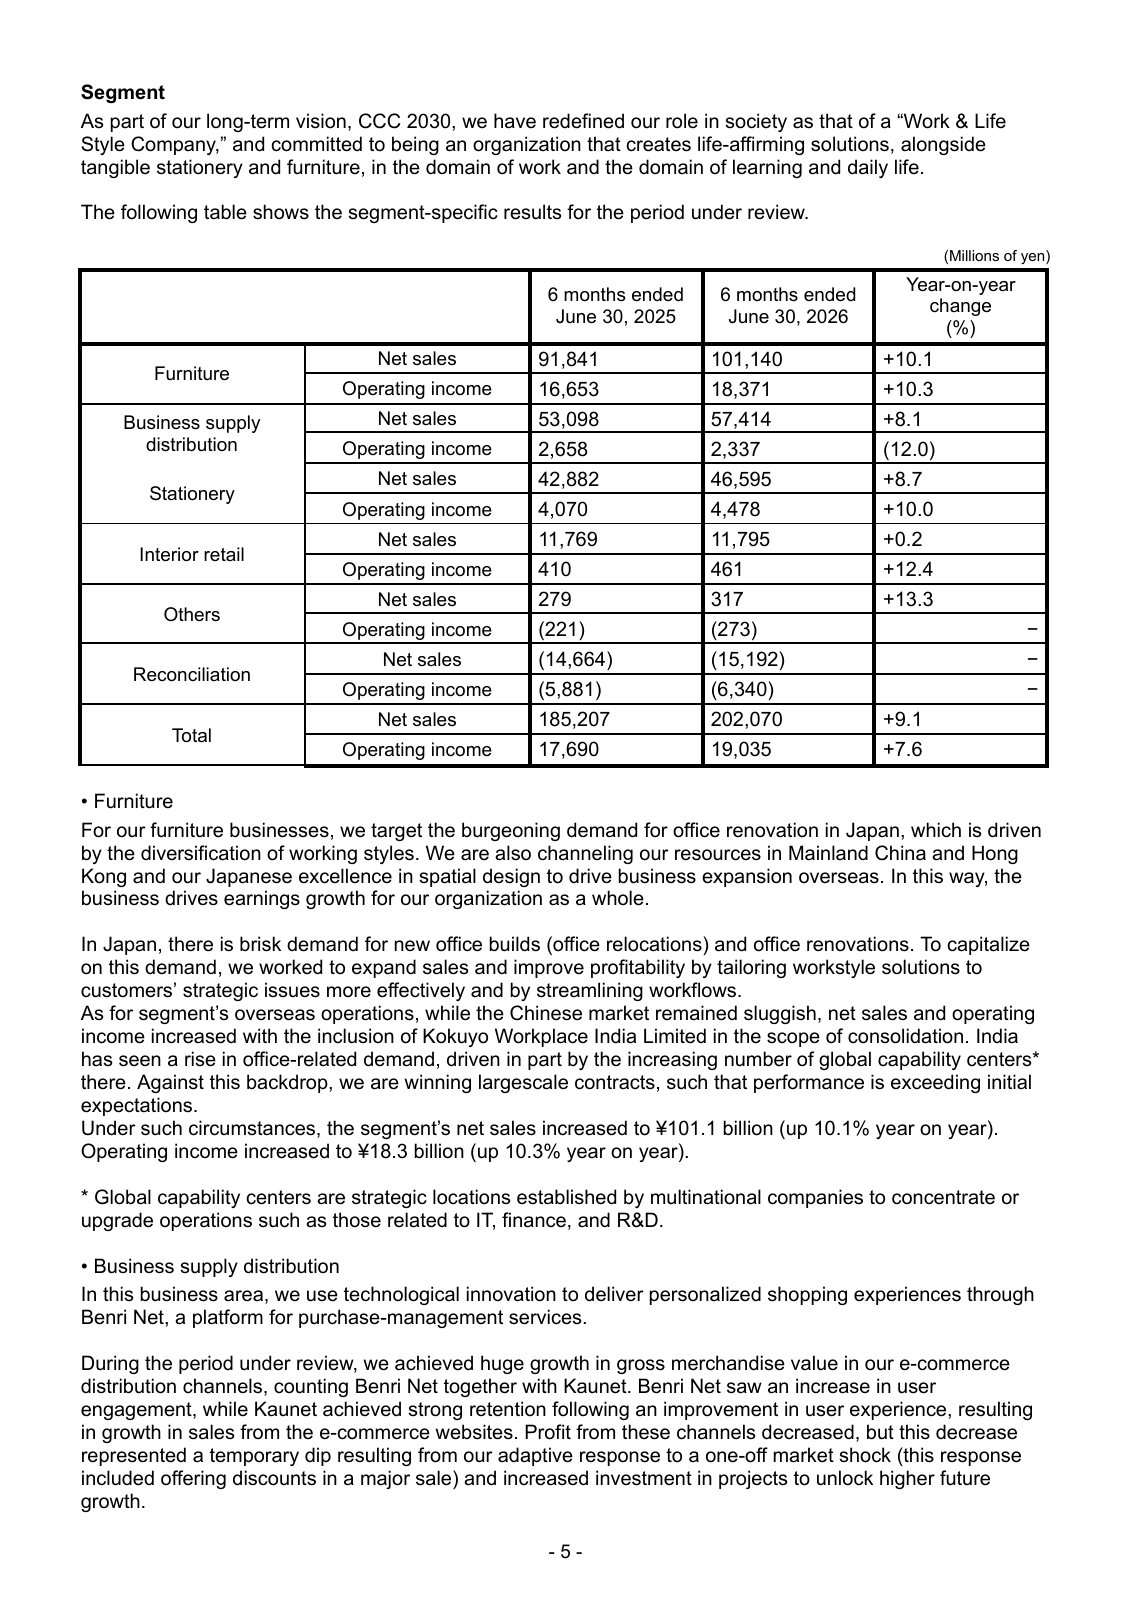
Kokuyo’s stationery business grew segment sales 8.7% to ¥46.595 billion in the first half of 2026, while operating income increased 10.0% to ¥4.478 billion. The July 31 filing shows growth in Japan and China alongside tougher competition in India.
| Stationery segment, January–June | 2025 | 2026 |
|---|---|---|
| Sales, including intracompany sales and transfers | ¥42.882bn | ¥46.595bn |
| Operating income | ¥4.070bn | ¥4.478bn |
| Operating margin on segment sales, calculated | 9.5% | 9.6% |
Margin is operating income divided by the segment-sales figure, rounded to one decimal place. The segment measure includes transactions within the group. Source amounts are rounded to millions of yen.
Campus is the growth strategy, not just a label
In Japan, Kokuyo says its Campus strategy combines stationery with study methods and new product launches. It credits that approach with higher consumer sales. In China, new products, retail expansion and e-commerce helped it grow despite weak economic conditions; the company specifically highlights its focus on secondary-school girls.
India tells a different story: increased competition affected performance. Kokuyo does not quantify each country’s stationery contribution in this release, so the overall gain should not be read as an identical improvement across markets.
The number to keep separate
The stationery segment’s ¥46.595 billion includes ¥10.975 billion of intracompany sales and transfers. Its sales to outside customers were ¥35.619 billion. Those internal transactions are eliminated when Kokuyo calculates consolidated group sales; adding segment totals together would overstate the group’s revenue.
Across all businesses, including furniture and distribution, Kokuyo reported ¥202.070 billion in sales, up 9.1%, and ¥19.035 billion in operating income, up 7.6%. It left the full-year group forecast unchanged at ¥390 billion in sales and ¥27 billion in operating income.
The stationery result gives a more useful view of the business behind Campus than the group headline alone: revenue is growing, profitability is edging higher, and the regional strategy matters. The filing does not isolate mechanical-pencil sales. Original issuer results, pages 5–6 and 14 of the report.