Kokuyo has approved ¥28 billion in acquisition funding for its planned takeover of Vietnam’s Thien Long Group. Behind that large number is a more specific industrial story: an established writing-instrument manufacturer, a growing export business, and a regulatory commitment to increase research and development in Vietnam.
The Japanese company’s board authorized the capital injection on September 30 into its wholly owned Singapore subsidiary, Synergy Investing ASIA. The funding disclosure leaves the payment date undetermined and makes implementation conditional on required Vietnamese approvals. It records an authorization, rather than confirming that the money has been transferred or the acquisition completed.
Buying a manufacturing and distribution base
Kokuyo set out the transaction in December 2025. It proposed acquiring Thien Long An Thinh, a holding company owning 46.82% of Thien Long Group, then buying up to a further 18.19% through a public tender offer. Together, those steps would give it up to 65.01%, subject to the offer’s outcome and transaction terms.
The original estimated purchase consideration was ¥27.6 billion. September’s ¥28 billion announcement concerns capital for the acquisition subsidiary; it should not be read as a newly announced purchase price.
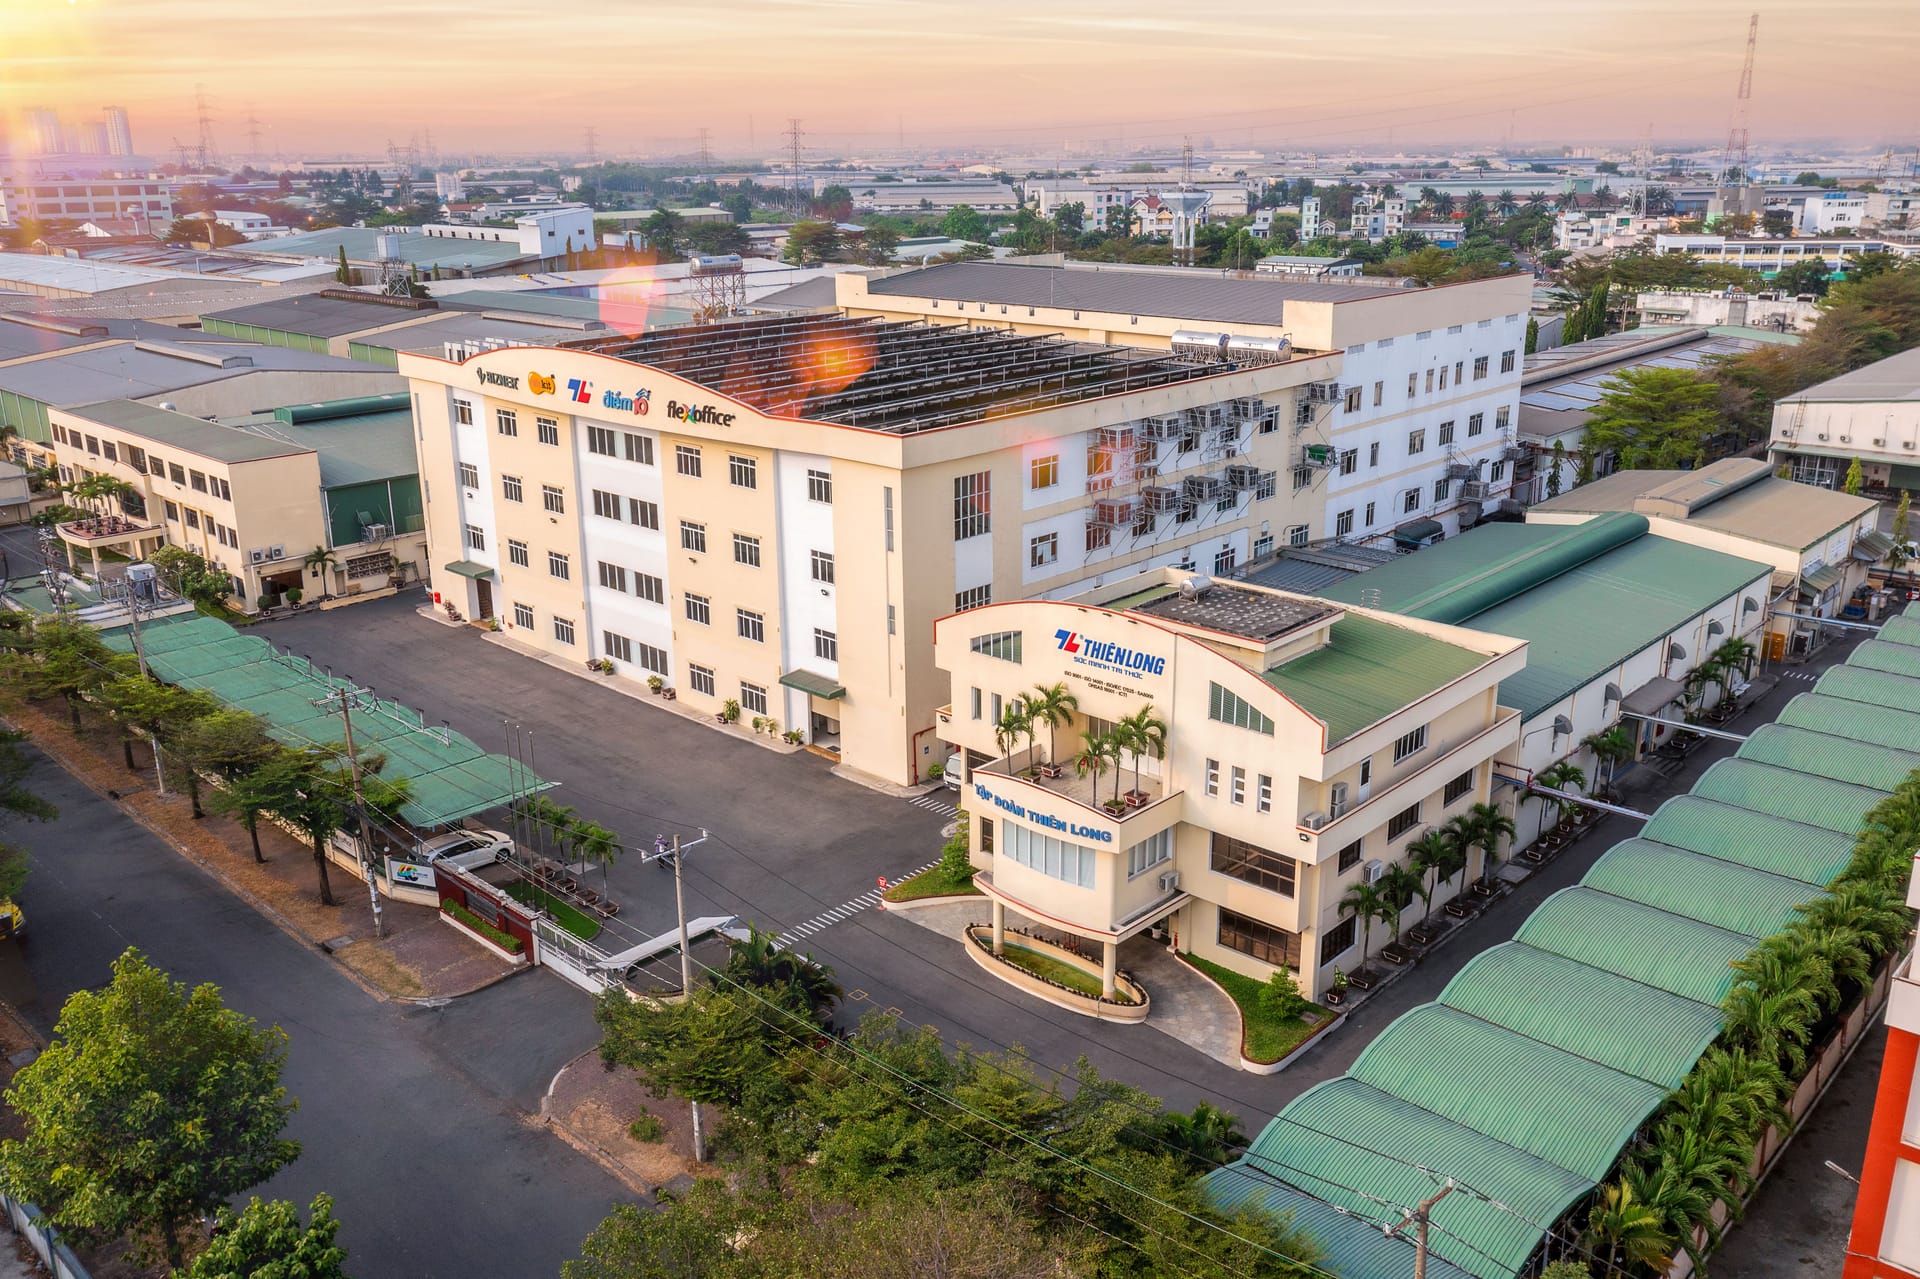
The rationale reaches beyond owning another brand. Kokuyo wants to combine Thien Long’s writing-instrument development, manufacturing and procurement capabilities with its own product planning and marketing, and use Thien Long’s distribution network to expand in ASEAN. The companies already had a writing-instrument manufacturing agreement in 2025, before the proposed acquisition.
A pencil maker inside the wider business
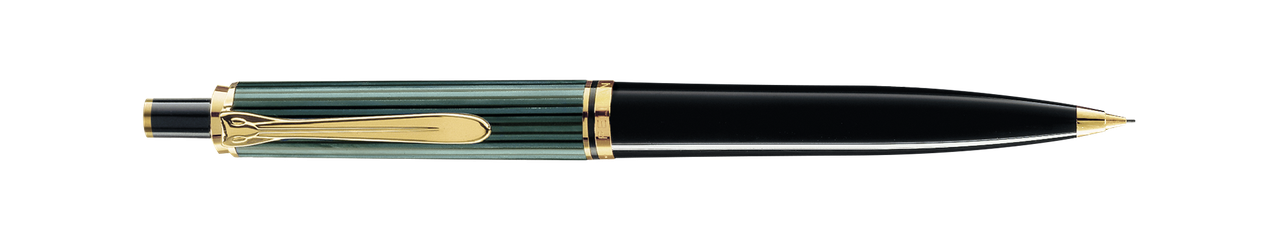
Thien Long’s range extends from school and office supplies to drawing materials and writing instruments. Its PC-030, for example, takes 2 mm lead and incorporates a sharpener in its top.
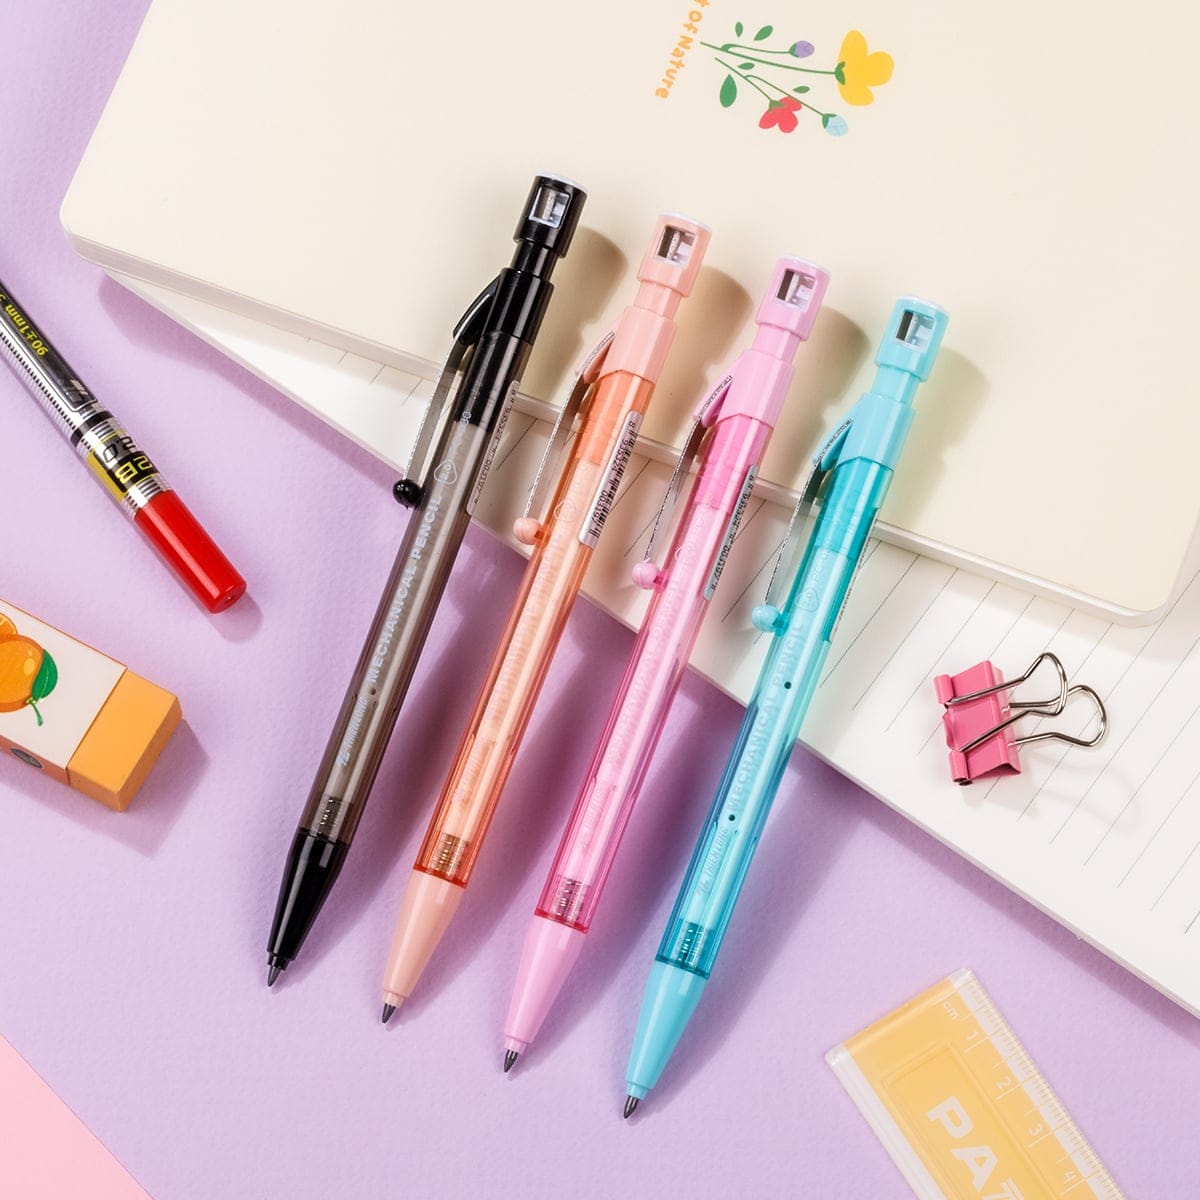
The business is also becoming more international. In its September investor newsletter, Thien Long reported revenue of VND 3,183 billion for the first eight months of 2026, up 13.0%. Export revenue grew faster: 21.2%, to VND 948 billion. The company attributes that export growth to international contract-manufacturing partnerships and continued investment in capacity and product quality. These are unaudited group figures, rather than a measure of pencil sales.
The clearance comes with an R&D commitment
Vietnam’s National Competition Commission granted conditional competition clearance on September 9, publishing its notice on September 21.
The decision’s conditions require the company group to increase annual R&D investment in Vietnam by VND 3 billion over the previous year’s level, for at least five consecutive years after the transaction year. That is an annual step up in investment, not a VND 3 billion total research budget. The conditions also address R&D staffing and the number of successfully commercialized new or improved product lines.
That makes product development something concrete to follow as the deal progresses. It does not specify a new pencil mechanism or model, but it gives readers a more useful yardstick than an acquisition’s promise of growth alone.
Competition clearance does not establish that every approval or transaction step is complete. The company disclosures reviewed for this report do not confirm completion of the acquisition or tender offer. For now, the documented developments are the funding authorization and the conditions attached to competition clearance; ownership completion and the resulting product investment remain the next milestones.