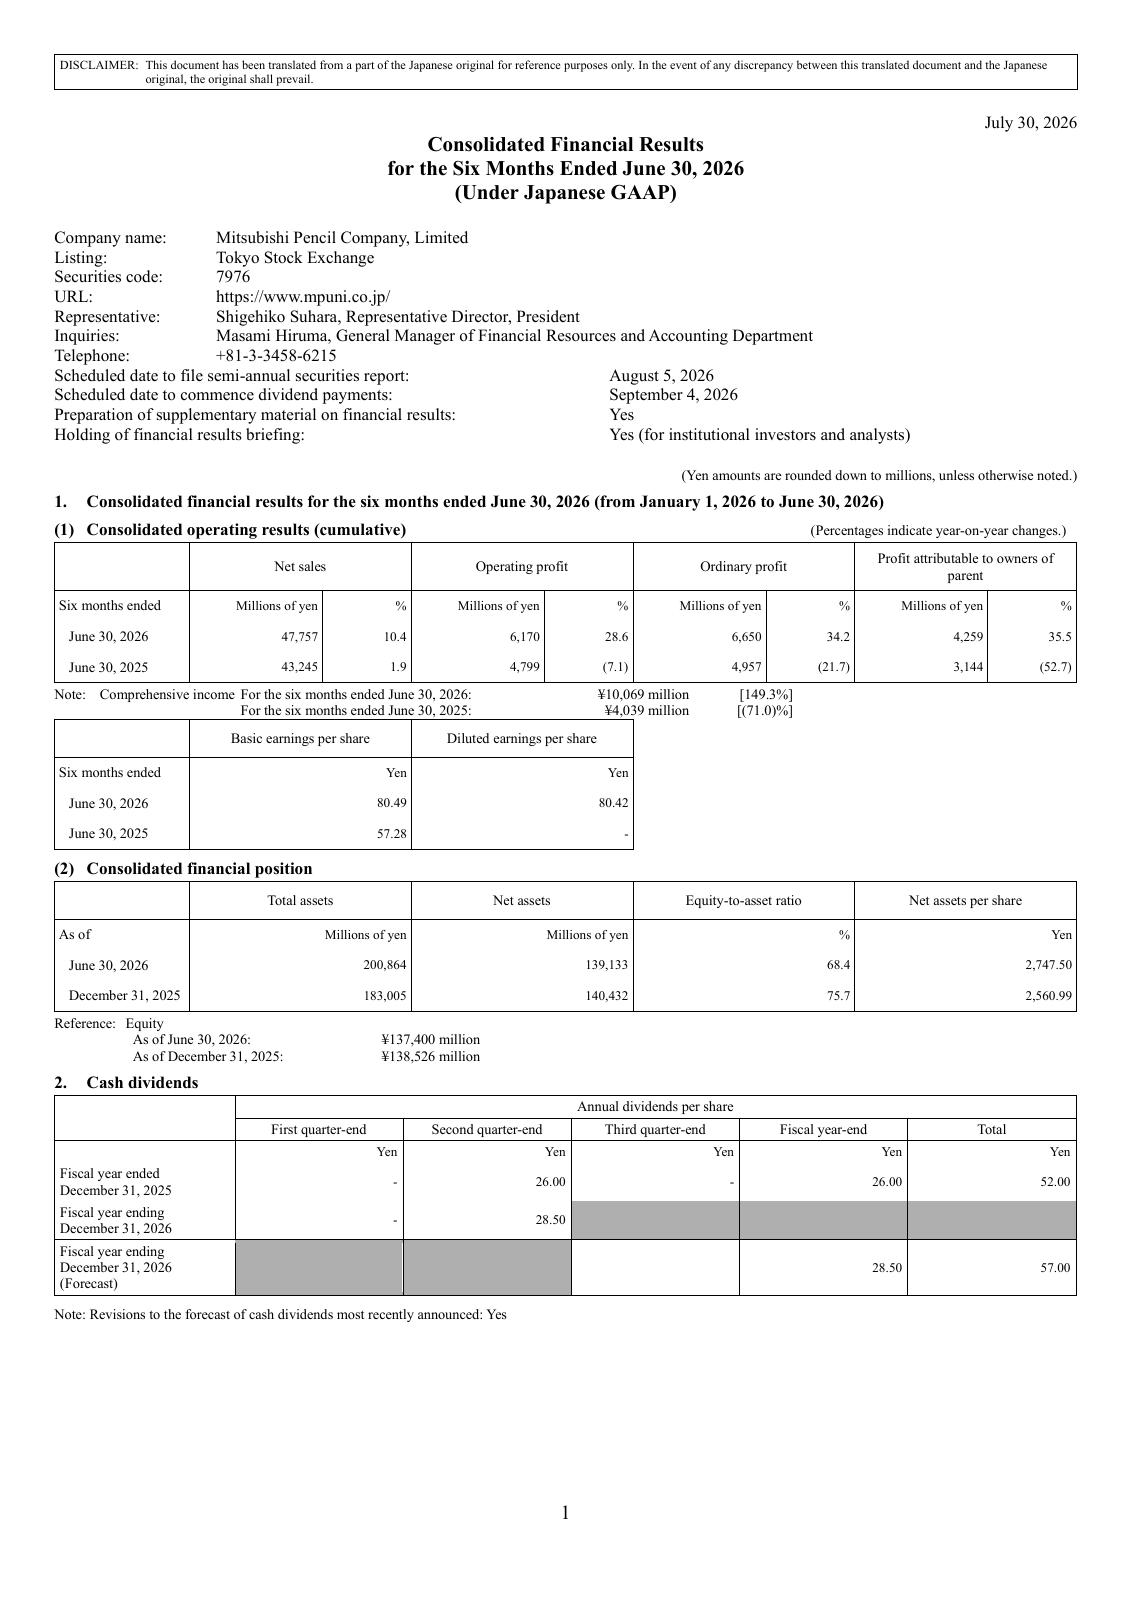
Mitsubishi Pencil reported ¥47.757 billion in first-half sales, up 10.4%, and ¥6.170 billion in operating profit, up 28.6%, on July 30. Profit grew substantially faster than revenue.
| January–June | 2025 | 2026 |
|---|---|---|
| Sales | ¥43.245bn | ¥47.757bn |
| Operating profit | ¥4.799bn | ¥6.170bn |
| Operating margin, calculated | 11.1% | 12.9% |
Margin is our calculation: operating profit divided by sales, rounded to one decimal place.
The margin gain is approximately 1.8 percentage points. Profit attributable to owners of the parent also increased, reaching ¥4.259 billion, up 35.5%. That bottom-line measure includes items beyond operating profit, so it should not be substituted for the operating margin above.
A higher bar for the full year
The company raised its full-year sales forecast from ¥94.0 billion to ¥95.5 billion, and its operating-profit forecast from ¥10.5 billion to ¥11.5 billion. The latter is a 9.5% increase over the previous forecast, not a year-on-year growth rate.
The revision cites first-half performance and the continued weakness of the yen. These are consolidated company results and forecasts; they do not isolate Kuru Toga, mechanical pencils or individual brands.
The manufacturer is generating more operating profit from each yen of reported sales and has increased its expectations for the year. The weak yen forms part of management’s explanation for the forecast; these figures alone cannot separate stronger product demand from currency effects.
Sources: First-half results; forecast revision. Both are original issuer disclosures hosted in the public TDnet filing archive.